September 22, 2026 Weekly Market Brief
US diesel averaged a record $6.285 a gallon on 14 September 2026, up 68 percent in a year. Splitting the wholesale price into the crude that goes in and what refiners charge to turn it into diesel shows that 58 percent of the rise since the Iran war began came from refining, which has tripled, rather than from crude oil. The Strategic Petroleum Reserve holds crude, not diesel, and the only federal reserve of actual diesel holds about 1 million barrels, roughly seven hours of US use.

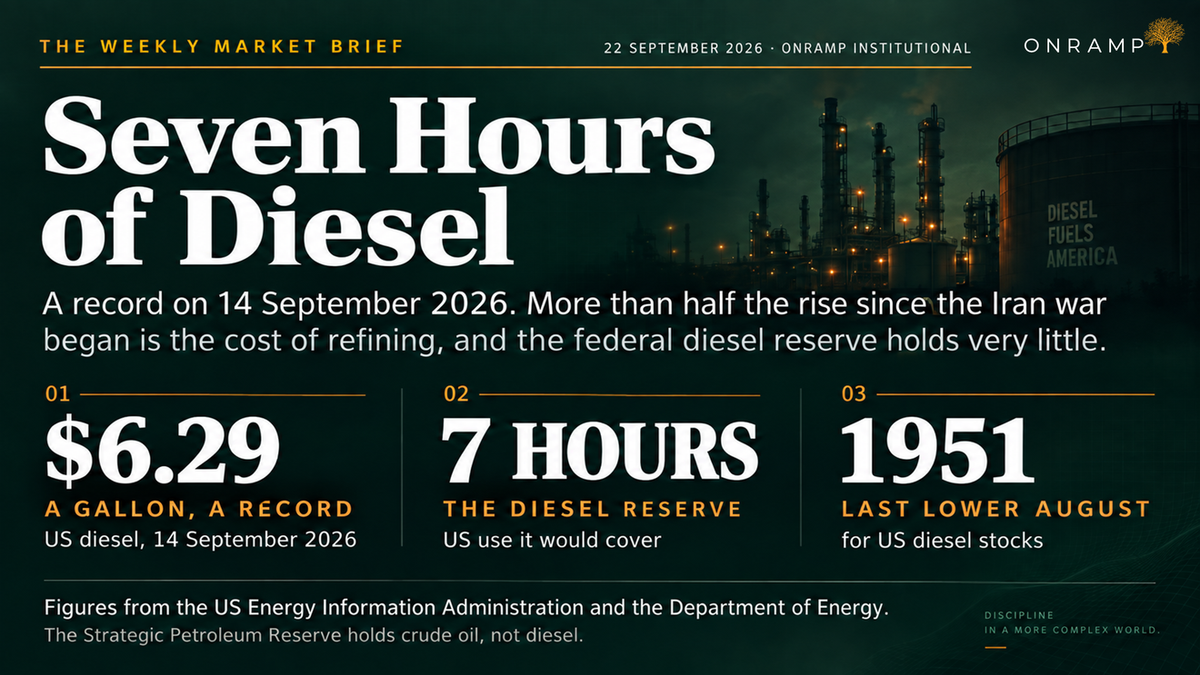
US diesel hit a record on 14 September 2026. More than half the rise since the Iran war began is the cost of refining. And the only federal stock of diesel would last the country about seven hours.
The Record
US diesel averaged $6.285 a gallon on 14 September 2026. That's a record, according to the Energy Information Administration. The old high was $5.81 in June 2022. A year earlier diesel cost $3.74. So it's up 68 percent.
More than half the rise since the Iran war began came from refining, not crude oil. And the government's fuel reserves are almost all crude oil.
What a Refinery Does
A refinery splits crude oil into gasoline, diesel, jet fuel and heating oil. Diesel, jet fuel and heating oil come out of the same part of the barrel. They use the same equipment. So when diesel runs short, a refinery can't simply make more. It would have to make less jet fuel and heating oil. And those are short too.
Where the Diesel Went
The EIA says the world lost a lot of diesel this year. It came from three places. The Middle East, Russia and China. The Middle East is the Iran war. In Russia, Ukrainian drones have hit refineries. So in July 2026 Moscow banned diesel exports. It has since extended the ban to the end of the year.
The US has filled part of the gap. The EIA says US net exports of diesel and heating oil have run at or near a five-year high. That's been true every month since February 2026. European buyers lost their Russian supply. And they're paying more than American buyers.
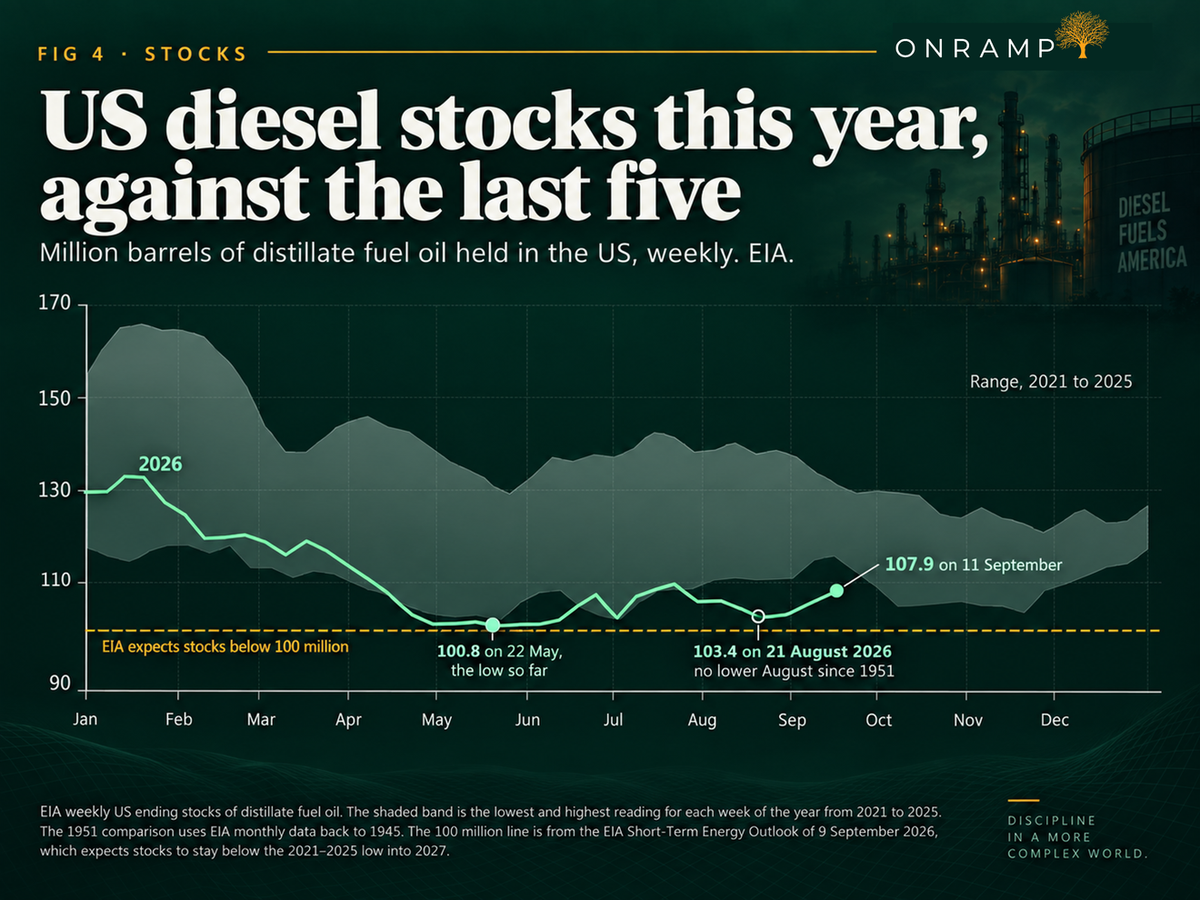
So diesel has been leaving the country while stocks at home ran down. They fell to 103.4 million barrels in the week to 21 August 2026. The last August with lower stocks was in 1951.
Crude and Refining, Separated
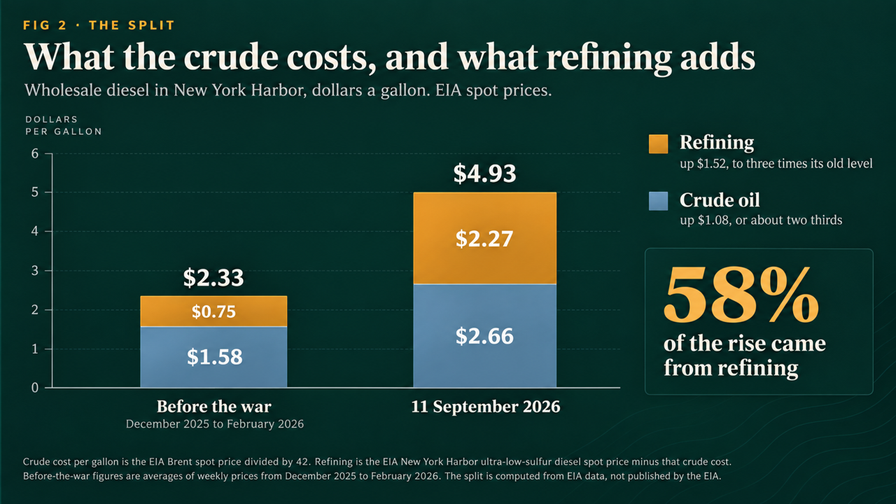
The wholesale price of diesel has two main parts. One is the cost of the crude oil that goes in. The other is what refiners charge to turn it into diesel. The industry calls that the crack spread. The refining part has tripled since before the war. The crude part is up about two thirds.
The numbers come from the EIA's wholesale diesel price in New York Harbor and its Brent crude price. From December 2025 to February 2026, before the war, diesel averaged $2.33 a gallon. The crude in it cost $1.58. Refining added 75 cents. On 11 September 2026 diesel was $4.93. The crude cost $2.66. Refining added $2.27.
So the crude part rose by $1.08 a gallon and the refining part by $1.52. Refining is 58 percent of the rise.
Two Reserves
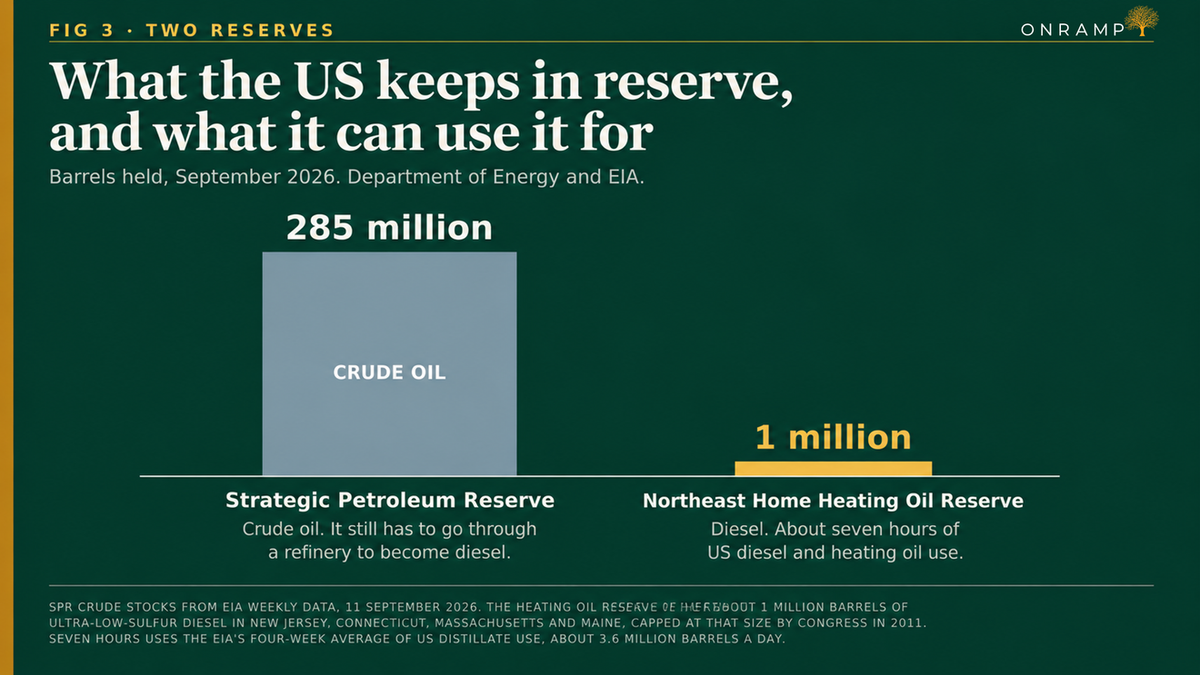
The Strategic Petroleum Reserve holds crude oil. It had 285 million barrels on 11 September 2026. Releasing some can bring down the crude part of the price. But the crude still has to go through a refinery. So the refining part stays where it is.
The only federal reserve of actual diesel is the Northeast Home Heating Oil Reserve. It holds about 1 million barrels. They sit in terminals in Maine, Massachusetts, Connecticut and New Jersey. Congress capped it at that size in 2011. It's been used in an emergency once, after Hurricane Sandy in 2012.
The US uses about 3.6 million barrels of diesel and heating oil a day. So the reserve would cover the country for about seven hours. In its 2021 budget request the Energy Department proposed closing it. It said the reserve had never been used for its intended purpose.
The Other Tool
The second tool is interest rates. The Fed raised its rate by a quarter point on 16 September 2026. It was the first rise since July 2023. Higher energy prices were part of the reason.
A rate rise can slow spending and stop high prices spreading. It can't add refining capacity. Kevin Warsh, the Fed chairman, said as much at his press conference. According to CNBC, he said the Fed can't stop price shocks on things like oil by itself.
The real fix is more refining. And the US was closing refineries before the war. LyondellBasell shut its Houston refinery in early 2025. In September 2025 the EIA said two California refineries planned to close within two years. Between them they had 284,000 barrels a day of capacity.
What Happens Next
The EIA's September outlook came out on 9 September 2026. It has crude getting cheaper and diesel staying tight.
It has Brent crude at about $90 a barrel for the rest of 2026. Then $74 in 2027. Diesel stocks stay below the lowest level of the last five years. That lasts through the end of 2026 and most of 2027. The refining margin stays above $2 a gallon through November 2026. Then it narrows slowly through mid-2027. And the EIA says damage to Russian refineries will hit the world market through the first half of 2027.
Stocks have come up a little since the August low. They were 107.9 million barrels on 11 September 2026. The EIA finished its forecast on 3 September 2026, before most of that rise.
The heating season starts next. The EIA counts heating oil and diesel as the same fuel. And most American homes that heat with oil are in the Northeast.
What it means for a bitcoin holder
The link to bitcoin is indirect. It runs through inflation. Nearly everything in the US travels by truck at some point. So diesel feeds slowly into the price of nearly everything. The EIA has that pressure lasting into 2027. And a rate rise can't reach the refining part of it.
That's a real point for anyone holding cash.
SOURCES AND NOTES: US Energy Information Administration, weekly retail on-highway diesel price (series EMD_EPD2D_PTE_NUS_DPG): $6.285 on 14 September 2026; previous record $5.810 on 20 June 2022; $3.739 on 15 September 2025. Pulled direct from eia.gov.
EIA weekly US ending stocks of distillate fuel oil (WDISTUS1): 103.391m barrels in the week to 21 August 2026, 107.859m on 11 September 2026. EIA monthly series (MDISTUS1): August stocks were last below 103.4m in 1951 (87.4m); August 1952 was 104.3m. Weekly and monthly series compared directly.
EIA weekly product supplied of distillate fuel oil (WDIUPUS2): four-week average about 3.6m barrels a day to 11 September 2026. EIA weekly SPR crude stocks (WCSSTUS1): 285.0m barrels on 11 September 2026.
EIA weekly New York Harbor ultra-low-sulfur diesel spot price and Brent spot price. Pre-war average taken over December 2025 to February 2026. Crude cost per gallon is Brent divided by 42. The split of the price rise is computed from these two series and is not an EIA figure.
EIA Short-Term Energy Outlook, released 9 September 2026, forecast completed 3 September 2026: distillate supply losses from the Middle East, Russia and China; net exports at or near a five-year high each month since February 2026; inventories below 100m barrels in September and below the 2021-2025 low through end-2026 and most of 2027; diesel crack spreads above $2 a gallon August through November, easing through mid-2027; Russian refinery outages affecting the market through first-half 2027; Brent about $90 in 2H26 and $74 in 2027.
US Department of Energy, Northeast Home Heating Oil Reserve pages and 2025 Sale Implementation Plan (about 1m barrels at Port Reading NJ, New Haven CT, Chelsea MA and South Portland ME); NEHHOR Releases page (Hurricane Sandy, 2012, the only emergency use). Congressional Research Service IF12205 (2011 cap under P.L. 112-74; FY2021 budget justification proposing disestablishment).
EIA Today in Energy, 24 September 2025: LyondellBasell Houston shut early 2025; two California refineries with 284,000 b/d combined planning to close within two years.
Federal Reserve decision of 16 September 2026 (CNBC, Fox Business, Bloomberg). Warsh's remark on oil price shocks is CNBC's paraphrase, not a direct quotation.
Russian diesel export ban, July 2026, extended to end-2026: widely reported (The Conversation, 18 September 2026). Secondary.
Market levels are as reported on the dates stated and are deliberately not restated at publication.
The Radar
What matters this week across digital assets, AI, and global markets.
Digital Assets & Regulation
Clarity fails 49 to 50
The Senate voted 49 to 50 on September 15. So the Clarity Act doesn't reach the floor. It needed sixty. One senator didn't vote. And Susan Collins voted no. Republicans added ethics language two days earlier. But the Democrats who negotiated the text still voted no. Senator Tillis entered a motion to reconsider. So the bill stays technically alive. And the SEC's offering rule takes comments until October 20.
The tax bill clears committee 38 to 5
The House Ways and Means Committee approved H.R. 10357 on September 16. It passed 38 to 5. And it's the first federal digital-asset tax bill to clear a committee. Fees of $10 or less would stop triggering a gain or loss. But wash-sale rules would apply to digital assets. So selling bitcoin at a loss and buying it back stops working. It raises revenue. And it has no ethics clause. No floor date is set.
The reserve bill clears committee 28 to 21
The House Financial Services Committee passed H.R. 8957 the same day. It was 28 to 21. And the bill puts the Strategic Bitcoin Reserve into law. Trump created it by executive order in 2025. So forfeited bitcoin would sit with Treasury for at least 20 years. And proof of reserves would be annual. But it doesn't order purchases. And Treasury and Commerce would study buying more without borrowing or new taxes.
AI & Financial Infrastructure
The labs ask to slow down
Anthropic's chief executive Dario Amodei published an essay on September 12. It asks frontier labs to pace how fast models improve. And Sam Altman agreed the same day. Altman also told Fortune that OpenAI won't list in 2026. But pacing doesn't mean stopping, he said. So on September 14 the Philadelphia semiconductor index fell 5.9 percent. Its worst day since July.
Moody's prices the power
Moody's Ratings published its estimate on September 14. The data center buildout needs 45 gigawatts of new generation by 2030. And that costs about $110 billion. And more than 30 gigawatts would be gas. Data centers would use 10 percent of US electricity by then. So bills could rise $25 billion to $30 billion a year. But data centers would pay up to $15 billion of that directly.
A trade for faster hookups
Nvidia, Google and Emerald AI launched the AI Energy Management Alliance on September 16. Data centers would cut their draw when the grid is stressed. And utilities would connect them faster in return. So a flexible site would move training to off-peak hours. Or it can run on batteries. And it's voluntary. But the rules for measuring it come next.
Geopolitics & Markets
The Fed hikes
The Fed raised rates a quarter point on September 16. So the range is now 3.75 to 4 percent. And it was unanimous. It's the first increase since July 2023. Sixteen of the 18 dots want at least one more this year. And four want two. For 2027 the committee splits eight for a hike, six for a hold and four for cuts. Warsh said the Fed can't move any single price. But it can stop a price shock spreading.
Japan hikes too
The Bank of Japan raised its policy rate to 1.25 percent on September 18. And that's the highest since 1995. The vote was 7 to 2. Toichiro Asada and Ayano Sato voted to hold. The last hike was in June. So the gap between hikes has halved to three months. It's the sixth increase since negative rates ended in March 2024. But Ueda didn't promise more.
A permanent US base in Poland
Trump wrote on September 17 that a permanent US Army base in Poland is close. And he said the location would be announced soon. Poland asked formally in June. It hosts US troops on rotation. So a permanent base would be new. But Reuters noted no decision has been taken. The same day, airports at Lublin and Rzeszow closed for a few hours during Russian strikes. And on September 13 a Russian drone hit 800 meters from a crossing into Poland. Tusk has said Russia may attack NATO states and call it an accident.
The Week in Numbers
| Indicator | Reading |
|---|---|
| The Fed's new range, its first hike since 2023 | 3.75-4% |
| The Bank of Japan's rate, highest since 1995 | 1.25% |
| Fed dots that want at least one more hike this year | 16 of 18 |
| Comment deadline on the SEC's offering rule | Oct 20 |
| Minimum hold for forfeited bitcoin under the reserve bill | 20 years |
| The chip index's fall on September 14 | 5.9% |
| Moody's cost for 45 gigawatts of new generation by 2030 | $110B |
| The Clarity Act cloture vote on September 15 | 49-50 |
What to Watch This Week
| Date | Why it matters |
|---|---|
| Sept 23 | BitMEX closes at 04:00 UTC. |
| Sept 24 | Xi Jinping arrives at the White House. Japan's new policy rate takes effect the same day. |
| Oct 5 | CME's futures on GPU rental rates are due to start trading, pending review. |
| Oct 20 | Comments close on the SEC's Regulation Crypto Assets proposal. |
| Oct 29-30 | The Bank of Japan meets again. |
| Nov 10 | China decides whether to extend or lift the suspended controls on erbium and four other rare earths. |